First, let’s look at the three types of accounts by their tax treatment.
Tax-Deferred Retirement Accounts are funded with untaxed dollars (contributions are tax deductible, either through salary-deferral or on your tax return). However, future withdrawals are fully taxed as ordinary income. Examples include 401(k)s and traditional IRAs.
Taxable Accounts are funded with after-tax dollars. Dividends and gains from sales receive preferential tax rates. Because you’re paying taxes in the years that income or sales occur, withdrawals aren’t taxed. These are usually mutual fund and stock accounts.
Roth Account contributions are not tax deductible. However, they grow tax-free forever, and withdrawals are never taxed.
It’s best to spread money across these three account types while you are working. This will give you some flexibility to manage your taxes in retirement, which could help your money last longer. Having different types of accounts also provides options for early retirees.
Optimal investment and withdrawal strategies are different for everyone. Factors include age, tax brackets, employer plan features, and investable income. Powerful retirement planning is best done well in advance and then annually while taking distributions.
Retirement planning is one of the most important things that we do for clients. We would be happy to discuss your situation and how we might be of service.
Many families list paying for a child’s college education as an important financial goal, yet are unsure how much to save. College tuition costs have increased much faster in recent decades than any other household expense. J.P. Morgan recently projected that a four-year college education for a child born today will cost between $250k and $580k (ranging from public in-state tuition to private tuition). At the same time, financial aid awards have declined.
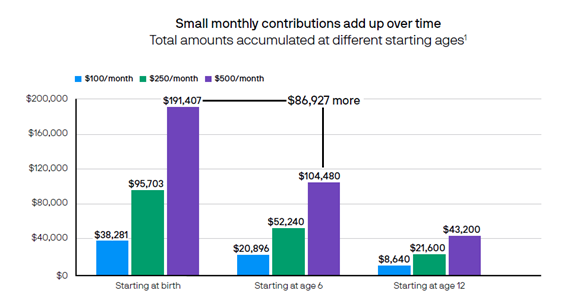
If you’re the parent of a newborn, the need for college planning may seem far in the future. But starting early can make a huge difference, even if making small monthly contributions.
A tax-advantaged savings vehicle has the potential to grow faster, as taxes aren’t taking a bite out of your investment returns.
In honor of National 529 Day on May 29th, here we highlight some facts about 529 accounts as a tax-advantaged vehicle for saving and investing for college.
You may get an income-tax break on contributions made to a 529 offered by the state you live in.
Money saved in a 529 has the potential to grow tax-free. Earnings on the money contributed are not taxed while in the 529 account, and money can be withdrawn free from federal income tax if used for qualified educational expenses, including an amount for room and board, and even an annual amount for K-12 education.
Most states also don’t impose state income tax on qualified withdrawals.
Taking money out of a 529 for non-educational expenses triggers tax and penalty only on the gains.
The beneficiary of a 529 account can be changed at any time to another family member or even to yourself. And there is no limit on how long a 529 account can exist – theoretically allowing an account to be passed down generations.
Family and friends can make contributions to your child’s 529, and if a non-parent is the account owner, the money in the 529 plan does not impact federal financial aid.
Subject to certain limitations, up to $35,000 of unused money in a 529 account can be rolled over to a Roth IRA in the beneficiary’s name, without any taxes or penalties related to taking money out for non-educational expenses.
1 J.P. Morgan Asset Management. This hypothetical example illustrates the future values at age 18 of different regular monthly investments for different time periods. Chart also assumes an annual investment return of 6%, compounded monthly. Investment losses could affect the relative tax-deferred investing advantage.
Most 401(k) and other retirement plans offer Target Date Funds (TDFs) as a default choice. They have become increasingly popular for a few good reasons but are rarely the best solution once your accounts achieve some size.
Let’s look at how they work and whether they are the most efficient choice for you.
TDFs are a great choice for beginners, or when you join a new employer plan. There is usually a lineup of funds targeting retirement dates in increments of five or so years. The concept is that the fund becomes increasingly conservative as the target date approaches, but that is a one-size-fits-all approach that can’t take your unique needs into account.
So, when are TDFs not the best investment choice?
To start, all of your money is invested with one fund family, instead of getting different approaches and methodologies. These funds are also usually invested across all asset classes and industries instead of those best suited to the current economic environment. They also evenly spread bond exposure instead of actively selecting the most appropriate bond sectors.
The biggest challenge with TDFs is that you don’t want all your investments too conservative as you enter retirement.
Yes, you want to make sure that you have some conservative assets to draw from during rough patches, but you still need growth during retirement to keep pace with inflation.
Here are a few things to consider:
· Do you actively rebalance your accounts?
· Does your plan have tools to evaluate your allocation vs. your goals and timeframes?
· Do you compare what you own against what’s available?
· Have you considered the advantages of an IRA for funds in an old employer plan?
· Are you layering investment risks to match your goal timeframes?
Changes to the FAFSA form and the formula for determining a family’s need for aid are changing, effective for the 2024-2025 school year. While all the changes are beyond the scope of this post, here we highlight two from a financial planning perspective.
Parent Income:
Contributions (pre-tax salary deferrals) to employer retirement accounts are no longer added back to parent income. This could be an additional incentive for parents with employer plans to max out contributions in years that the FAFSA looks at income. The FAFSA looks at the year two years prior to the beginning of the school year. For example, the 2024-2025 school year looks at 2022 income. Note that this change only applies to contributions that come straight from a salary reduction. Contributions to IRAs that are deductible on the tax return are still added back to parent income.
Grandparent Contributions: Up until now, while grandparent (or other non-parent) owned 529 accounts did not count towards a parent or student’s assets, withdrawals from said account counted as income to the student which had to be reported on the FAFSA. This could reduce the student’s aid eligibility. With the changes, withdrawals from a third-party owned 529 account will no longer count as student income. Grandparents can now maintain a 529 account for their grandchildren and distribute funds without impacting aid eligibility.
Because of these changes, the 2024-2025 form will not be available until December this year. You can stay up to date on announcements at https://studentaid.gov/, or through college financial aid office websites.
Call us to review your investment approach (404) 941-2800.
19% of women report feeling confident selecting investments that align with their goals
This is a discouraging statistic from a recent survey conducted on women and investing. We know that a gender gap exists when it comes to investing – on average, data shows that women’s investment account balances are less than men’s. There are a few often-cited reasons for this. The gender pay gap still exists, and women statistically spend more time outside of the workforce, meaning that women may simply have less money to invest.
But there is another reason. Women tend to feel less confident taking investment risk and therefore hold more cash on the sidelines, hampering their money’s growth potential.
But there is a difference between taking risk, and taking inappropriate risk for your goals. Women tend to benchmark successful investing not by the return numbers themselves, but by progress towards goals – buying a house, funding an education, or retiring comfortably.
Defining your goals and their timeframes is the first step toward building the confidence to invest. Money that you don’t need for 10 or 15 years can afford to be invested for growth. The farther along the timeline your goal is, the more certainty you can have of capturing greater returns by investing.
When women do invest, they see results. On average, women outperformed their male counterparts by 40 basis points or 0.4% over a 10-year analysis
On the flip side, studies show that over time, women’s investment returns tend to outperform men’s, with women exhibiting less impulsive investment decisions and staying the course when there is market volatility.
Starting early is the most powerful thing you can do to put yourself on track. If you didn’t start early, start now. Women already have the proclivity to stay invested to meet their goals, we just need the confidence to invest in the first place!
I joined Integras Partners in 2022 wanting to broaden my impact on people’s lives, particularly groups that have been underserved by the financial advice community – groups like women and single earners, which I am also a part of. Integras Partners was already well suited to women investors – focusing on the partnership and the “why” behind financial goals.
I’ll be writing more about these areas in coming newsletters, as well as general financial wellness and investing topics that I hope you will find interesting.
If you are already charitably inclined there are two gifting strategies that you should be aware of, Qualified Charitable Distributions (QCDs) and gifting appreciated stock.
In Strategies for Charitable Giving – Part 1 we discussed the tax benefits of QCDs which can be done by IRA owners who are at least 70.5 years old. But what if you are younger and giving to charities? Are there any tax benefits available? Most people take the standard deduction since the Tax Cuts and Jobs Act increased it, and if you’re not itemizing you lose the ability to deduct charitable contributions.
If you have appreciated stock (owned for more than a year) in a taxable investment account, donating stock instead of cash could provide a tax benefit to you and result in a greater gift to the charity.
Let’s look at an example.
Jim plans to donate to his favorite charity. He owns $30,000 of Microsoft stock that he purchased several years ago for $5,000. Jim is subject to 15% capital gains tax. If he were to sell the stock, he would pay $3,750 in taxes, leaving him with $26,250 to donate. If Jim is able to itemize his tax deductions, he would be able to deduct $26,250.1
If, instead, Jim donated the stock directly to the charity, he would avoid paying the capital gains tax. The charity receives the full $30,000 value, rather than $26,250. And if Jim itemizes, he may be able to deduct the full $30,000.1
To be eligible for a charitable deduction for this tax year, donations of stock need to be received by the end of the year.
Determining charitable giving strategies is one way that we partner with clients. We can help you determine if donating appreciated stock is right for your situation.
Call us to review your investment approach (404) 941-2800.